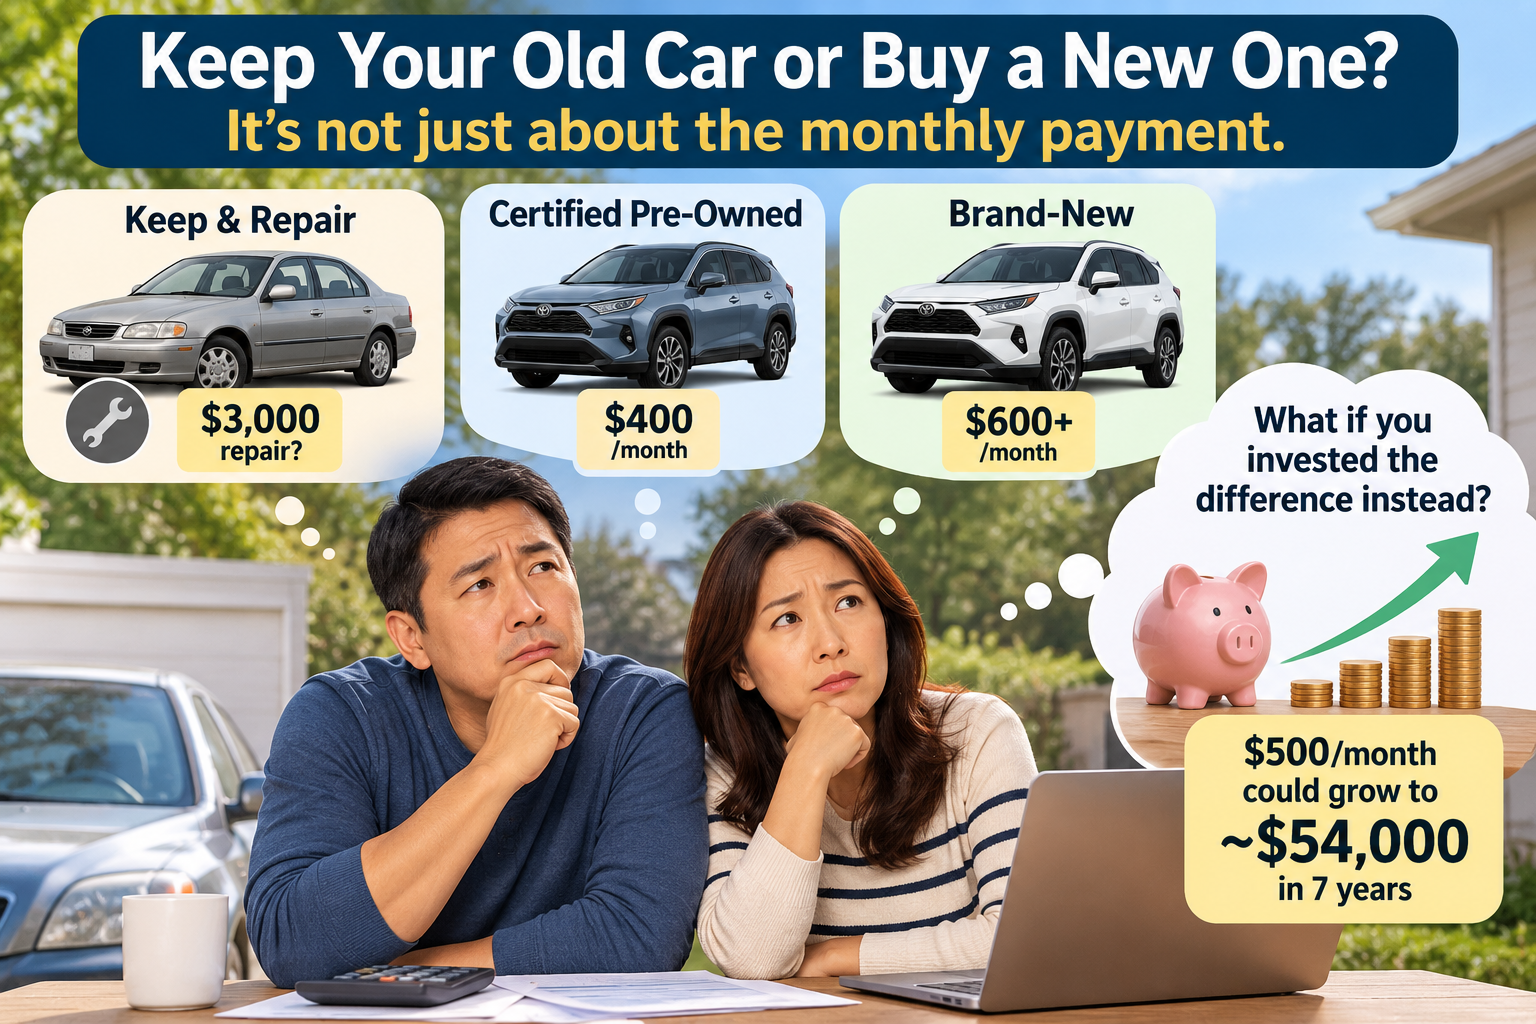
Is it better to repair your old car, buy a certified pre-owned vehicle, or purchase a brand-new one? Here’s how that decision could affect your family’s finances.
Is It Really Time for a New Car?
When you’ve been driving the same car for almost 10 years, you eventually start wondering whether it’s time for something new.
I understand the temptation. A newer car has better technology, updated safety features, and hopefully fewer unexpected trips to the mechanic.
But whenever I think about replacing a car, I also think about the monthly payment.
As a working parent, I know how quickly expenses add up. Between housing, groceries, children’s activities, and saving for retirement, adding another $500 or $700 monthly payment isn’t a small decision.
And here’s something I’ve started thinking about more:
What if keeping a reliable car for a few extra years could actually help build our family’s future wealth?
Let’s look at the numbers.
1. The Real Cost of Buying a New Car
A new car costs more than its sticker price.
According to Experian, the average monthly payment for a financed new vehicle was approximately $765 in the second quarter of 2026.
That’s $9,180 per year in payments alone.
You also have insurance, gas, maintenance, registration, and depreciation.
Depreciation is simply the value your car loses as it gets older.
AAA estimated that the average annual cost of owning and operating a new vehicle in 2026 was approximately $12,863.
That figure includes depreciation and financing costs, so it shouldn’t be added to loan payments as a separate expense.
For many middle-class families, transportation takes a surprisingly large portion of the household budget.
2. What If Your Old Car Needs a $3,000 Repair?
Imagine your 10-year-old car is worth $7,000, but the mechanic tells you it needs a $3,000 repair.
Your first reaction might be:
“Why would I spend $3,000 fixing a car that’s only worth $7,000?”
But here’s how I would look at it.
If that repair allows you to drive the car safely for another three years, the cost works out to approximately $83 per month.
Compare that with taking on a new car payment of $600 per month.
| Keep old car | Buy new car | |
|---|---|---|
| Immediate repair | $3,000 | $0 |
| Monthly loan payment | $0 | $600 |
| Payments over 3 years | $0 | $21,600 |
Of course, the older car will still need maintenance, insurance, and possibly additional repairs. And the newer car will have resale value.
But the comparison shows why a large repair bill doesn’t automatically mean replacing the car is the smarter choice.
Before deciding, I would ask a trusted mechanic whether the repair is likely to keep the vehicle reliable and safe for another few years.
3. How Much Could Keeping Your Car Save Over Five Years?
Let’s compare a paid-off older SUV with buying a $35,000 new SUV.
Here is a simplified example of five-year ownership costs.
| Expense over 5 years | Keep old SUV | Buy new SUV |
|---|---|---|
| Repairs and maintenance | $9,000 | $3,000 |
| Insurance | $7,500 | $11,000 |
| Gas | $10,000 | $8,000 |
| Registration and fees | $1,000 | $1,500 |
| Loan interest | $0 | $4,900 |
| Depreciation | $5,000 | $17,000 |
| Total cost | $32,500 | $44,400 |
Illustrative estimates assuming the old SUV is worth $7,000 today, the new SUV is worth $18,000 after five years, and the new vehicle is financed with a $7,000 trade-in. Actual costs will vary. Purchase taxes and dealer fees are excluded.
In this example, keeping the older vehicle saves approximately $11,900 over five years.
That’s money that could go toward emergency savings, college expenses, or retirement.
But what if your old car is no longer dependable?
That’s when I would consider another option.
4. Certified Pre-Owned Cars: A Smart Middle Ground
I don’t think the decision always has to be between keeping an old car and buying a brand-new one.
A Certified Pre-Owned (CPO) vehicle can be a good middle-ground option.
These are used vehicles that have gone through a certification process, often through a manufacturer’s authorized dealership.
Manufacturer-backed CPO programs typically offer inspections and some additional warranty protection, although the details vary.
For example:
| New SUV | CPO SUV | |
|---|---|---|
| Purchase price | $35,000 | $25,000 |
| Down payment | $5,000 | $5,000 |
| Loan term | 5 years | 5 years |
| Example interest rate | 6.5% | 7.5% |
| Monthly payment | ~$587 | ~$401 |
Illustrative financing example, excluding taxes and fees.
That’s approximately $186 less every month.
Over five years, the payment difference adds up to more than $11,000.
A CPO car may require more maintenance or have a shorter remaining life than a new vehicle. Still, it can be worth considering if you want something more reliable without spending as much.
I would compare the total price, warranty, maintenance history, and financing terms before choosing.
5. The Hidden Seven-Year Cost: Money You Could Have Invested
This is the part I find most interesting.
When we buy a car, we usually focus on whether we can afford the monthly payment.
But what about the money we could have invested instead?
Let’s say keeping your paid-off car allows you to save an extra $500 per month after accounting for repairs and other expenses.
What if you invested that $500 every month for seven years?
Assuming a hypothetical 7% annual investment return, compounded monthly:
| After 7 years | |
|---|---|
| Money you invested | $42,000 |
| Potential investment growth | ~$12,000 |
| Total investment value | ~$54,000 |
That’s approximately $54,000 that could be working toward your family’s financial future.
Here’s how different monthly savings could grow:
| Monthly investment | Potential value after 7 years |
|---|---|
| $200 | $21,600 |
| $300 | $32,400 |
| $400 | $43,200 |
| $500 | $54,000 |
| $600 | $64,800 |
These are hypothetical projections, not guaranteed returns. They assume seven full years of monthly contributions, 7% annual returns with monthly compounding, and no taxes or investment fees.
Of course, this isn’t a perfect comparison.
A newer car will still have resale value, while an older car may eventually need to be replaced. You may also have to stop investing the difference when your old car wears out.
But it illustrates an important concept called opportunity cost.
Opportunity cost is the financial benefit you give up when you choose to spend money on something else.
A new car might make your daily commute more comfortable, but it may also mean less money going toward investments.
That’s a trade-off worth understanding.
6. When Is Buying a Newer Car Worth It?
I don’t believe keeping an old car is always the right decision.
If your car has serious safety problems, breaks down frequently, or requires one expensive repair after another, replacing it may be the better choice.
Reliability matters, especially when you depend on your car for work and family responsibilities.
Before replacing a vehicle, I would consider three questions:
- Is my current car still safe and reliable? A trusted mechanic can help assess its condition.
- What will the replacement really cost? Include insurance, interest, depreciation, and maintenance—not just the monthly payment.
- How will this purchase affect my other financial goals? Will I still be able to save for emergencies, college, and retirement?
If replacing the car makes sense, I would compare a reliable used vehicle, a manufacturer-certified pre-owned vehicle, and a brand-new one before making the final decision.
Final Thoughts: Sometimes Keeping What You Have Is the Smarter Investment
I’ve come to realize that building wealth isn’t always about finding the next great investment.
Sometimes it’s about making thoughtful decisions with the money we already earn.
A car is important for everyday life, but it usually loses value over time.
Investments, on the other hand, have the potential to grow over the long term.
That doesn’t mean we should never enjoy a new car.
But if your current vehicle is safe, reliable, and paid off, keeping it a little longer could free up money for something more meaningful in the future.
Before replacing your car, ask yourself: Am I buying a car because I truly need one, or because I’m ready for something new?
The answer might help you make a decision that’s better for both your family today and your finances tomorrow.
Disclaimer: This article is for educational purposes only and does not constitute personalized financial advice. Vehicle costs, financing rates, maintenance expenses, and investment returns vary. Investment projections are hypothetical and are not guaranteed.
By Irene | Money Bloom Daily
Leave a Reply