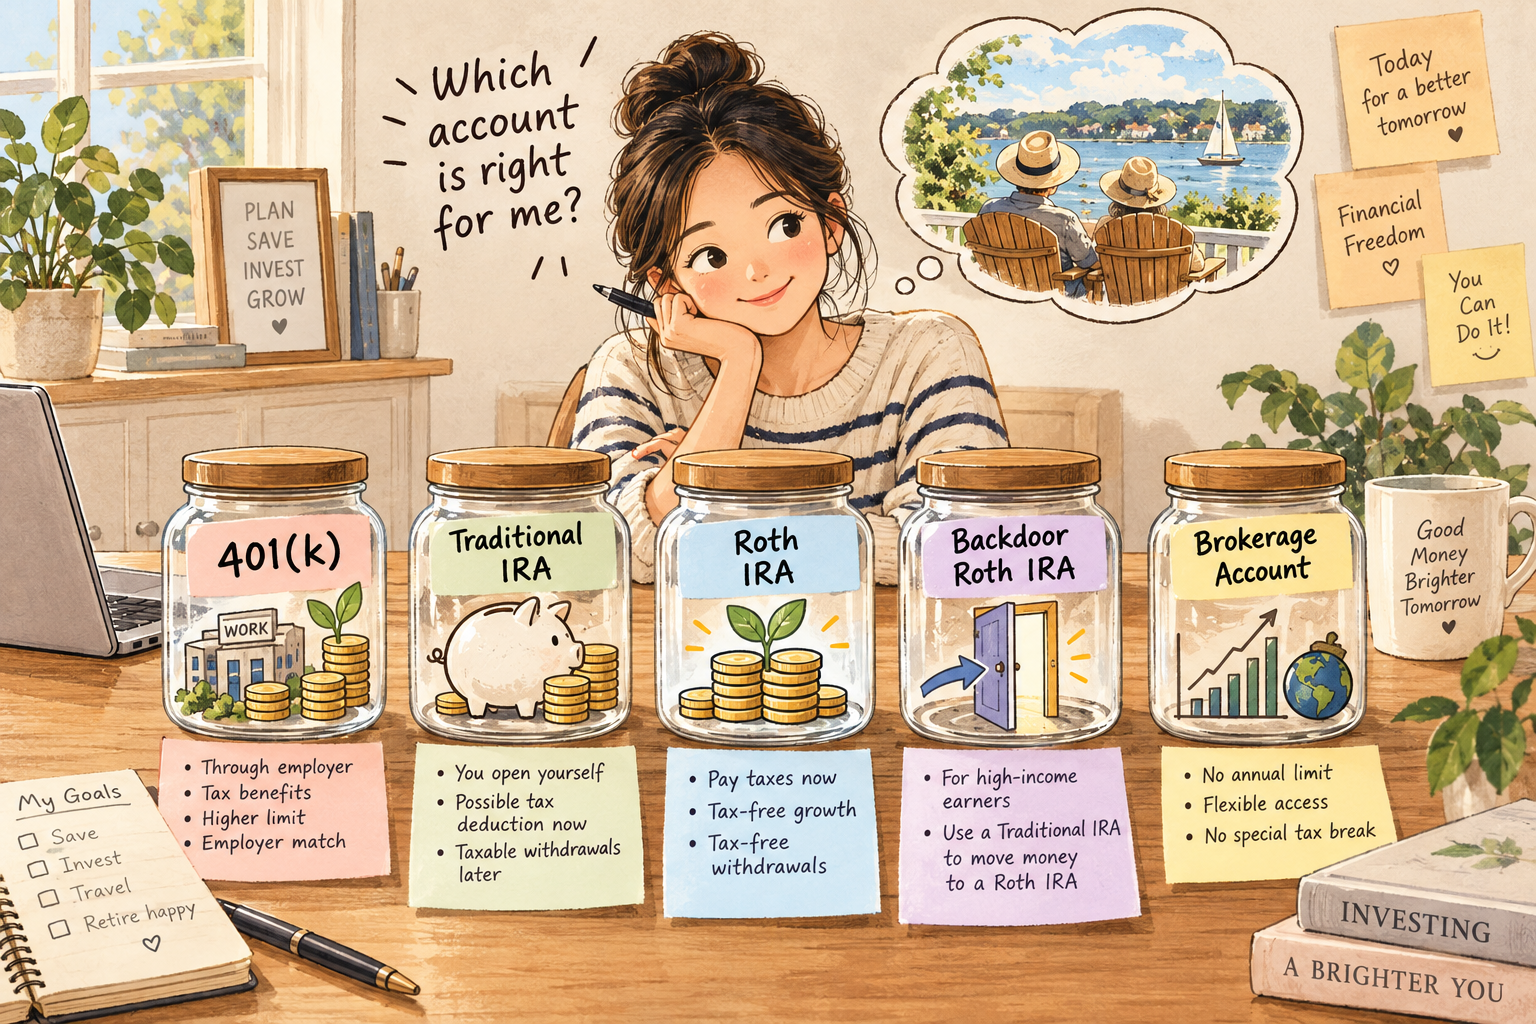
What’s the difference between a 401(k), Traditional IRA, Roth IRA, Backdoor Roth IRA, and brokerage account? And why do some people need a Backdoor Roth IRA to save for retirement?
When I first started learning about investing, I thought retirement planning was pretty simple.
You work, save money in your 401(k), and hopefully have enough to retire comfortably.
But as I started learning more, I discovered there were several different types of investment accounts.
401(k), Traditional IRA, Roth IRA, Backdoor Roth IRA, brokerage account…
Honestly, it was confusing.
Why do we need so many different accounts? Why does the government limit how much we can contribute? And why can someone with a higher income be prevented from contributing directly to a Roth IRA?
The more I learned, the more I realized something important.
Building wealth isn’t just about how much you invest. It’s also about how much you get to keep after taxes.
Let’s break everything down in a way that’s easy to understand.
1. First, What’s the Difference Between These Investment Accounts?
Before learning about a Backdoor Roth IRA, it helps to understand the accounts you may already have.
Retirement and Investment Accounts Compared
| Account | What Is It? | Tax Benefit | When Can You Withdraw? |
|---|---|---|---|
| 401(k) | Retirement account offered through your employer | Traditional: tax savings now. Roth: tax savings later | Generally after age 59½ without an early-withdrawal penalty |
| Traditional IRA | Retirement account you open yourself | Possible tax deduction now; taxable withdrawals later | Generally after age 59½ without an early-withdrawal penalty |
| Roth IRA | Retirement account you open yourself | Pay taxes now; qualified withdrawals are tax-free | Contributions generally anytime; earnings have additional rules |
| Backdoor Roth IRA | A way to put money into a Roth IRA when your income is too high | Same Roth benefits, but conversion may create taxes | Same Roth IRA rules, plus conversion-specific rules |
| Brokerage Account | Regular account for investing in stocks, ETFs, and other investments | No special retirement tax break | Generally anytime |
Think of these accounts as different containers for your investments.
You can often buy similar investments inside each account.
The biggest differences are how the money is taxed, how much you can contribute, and when you can withdraw it.
2. How Much Can You Contribute in 2026?
The IRS sets annual limits for retirement accounts.
Here’s a simple comparison for someone under age 50.
| Account | 2026 Annual Contribution Limit | Income Limit? |
|---|---|---|
| 401(k) | $24,500 | No general income limit for employee contributions |
| Traditional IRA | $7,500 | No upper income limit to contribute |
| Roth IRA | $7,500 | Yes |
| Backdoor Roth IRA | Shares the same $7,500 IRA limit | No income limit for conversions |
| Brokerage Account | No annual contribution limit | No |
Important: You cannot contribute $7,500 to a Traditional IRA and another $7,500 to a Roth IRA in the same year.
They share the same annual contribution limit.
A Backdoor Roth IRA doesn’t give you extra contribution room.
For people age 50 or older, the 2026 IRA contribution limit increases to $8,600.
Source: IRS 2026 Retirement Contribution Limits
3. Why Would Someone Choose a Roth IRA?
Let’s imagine two people each invest $7,500 annually for 25 years.
One uses a Traditional IRA, and the other uses a Roth IRA.
Assume both invest in the same funds and earn the same returns.
Their investments could grow to similar amounts before taxes.
But the difference comes when they withdraw the money.
Traditional IRA: Withdrawals are generally taxable. If you received tax deductions when contributing, you typically pay income taxes on that money when you withdraw it.
Roth IRA: You contribute money that has already been taxed. If you follow the withdrawal rules, you generally don’t pay income taxes on your investment earnings when you retire.
This is why Roth IRAs can be attractive for long-term retirement savings.
However, a Traditional IRA may be better for some people, especially if they qualify for a deduction and expect to pay lower taxes in retirement.
Neither account is automatically better for everyone.
4. Why Can’t Everyone Contribute to a Roth IRA?
Here’s where income limits become important.
For 2026, the IRS limits direct Roth IRA contributions based on income.
2026 Roth IRA Income Limits
| Filing Status | Full Contribution Allowed | Reduced Contribution | No Direct Contribution |
|---|---|---|---|
| Single | Below $153,000 | $153,000 to under $168,000 | $168,000 or more |
| Married filing jointly | Below $242,000 | $242,000 to under $252,000 | $252,000 or more |
These limits are based on modified adjusted gross income, which is a tax calculation that may be lower than your total salary.
For example, imagine a married couple living in New York.
One spouse earns $140,000.
The other earns $130,000.
Their combined annual salary is $270,000.
After certain adjustments, their income for Roth IRA purposes may be lower.
But if their modified adjusted gross income is still $270,000, they cannot contribute directly to a Roth IRA in 2026.
Does that mean they can’t use a Roth IRA?
Not necessarily.
This is where the Backdoor Roth IRA comes in.
Source: IRS Publication 590-A
5. What Is a Backdoor Roth IRA?
The name sounds complicated, but the basic idea is simple.
Imagine you’re trying to enter a room.
The front door is locked because your income is too high.
But there’s another legal entrance.
Instead of putting money directly into a Roth IRA, you first put it into a Traditional IRA.
Then you move that money into a Roth IRA.
That’s a Backdoor Roth IRA.
How It Works in Three Steps
Step 1: Open a Traditional IRA.
This is a retirement investment account you can open yourself.
Step 2: Contribute $7,500.
Use money you’ve already paid income taxes on, and don’t claim a tax deduction for this contribution.
Step 3: Move the money into a Roth IRA.
This is called a Roth conversion.
Once the money is in your Roth IRA, you can invest it for retirement.
Traditional IRA → Roth IRA → Long-term investing
That’s the basic process.
If you have no other pretax IRA money and the contribution hasn’t earned anything before conversion, you may owe little or no additional income tax on the conversion.
However, there’s an important tax rule we’ll explain shortly.
6. Can You Have Both a Roth IRA and a Backdoor Roth IRA?
Yes, but there’s a catch.
You cannot use both strategies to double your annual contribution limit.
A Backdoor Roth IRA isn’t a separate type of account.
It’s simply another way to put money into a Roth IRA.
For example, if you’re 40 years old and eligible to make direct Roth IRA contributions:
| Contribution Method | Amount |
|---|---|
| Direct Roth IRA contribution | $3,000 |
| Traditional IRA contribution followed by Roth conversion | $4,500 |
| Total IRA contributions | $7,500 |
You cannot contribute another $7,500 simply because you’re using the Backdoor strategy.
Also, if your income is above the direct Roth IRA limit, you cannot make the $3,000 direct contribution shown in this example.
What About Married Couples?
Each spouse can have their own IRA.
For 2026, a married couple under age 50 could potentially contribute:
| Person | Annual IRA Contribution |
|---|---|
| Spouse 1 | $7,500 |
| Spouse 2 | $7,500 |
| Combined | $15,000 |
They must meet the applicable income and compensation requirements.
7. Can You Contribute to a 401(k), Roth IRA, and Brokerage Account Together?
Yes!
This is something I wish I had understood earlier.
You don’t have to choose only one investment account.
You can use several accounts together because they serve different purposes.
Imagine you’re 40 years old and want to invest as much as possible.
Here’s one example.
| Investment Account | Annual Investment |
|---|---|
| 401(k) | $24,500 |
| Roth IRA or Backdoor Roth IRA | $7,500 |
| Brokerage account | $10,000 |
| Total Annual Investment | $42,000 |
This example assumes you qualify for the contributions and can afford to invest those amounts.
The brokerage account has no annual contribution limit, so you could invest more if your budget allows.
For a married couple where both spouses are under 50, eligible, and able to maximize their retirement contributions:
401(k): $24,500 × 2 = $49,000
IRA: $7,500 × 2 = $15,000
That’s $64,000 annually in retirement contributions, before employer matching.
They could also invest additional money in brokerage accounts.
8. What About a Mega Backdoor Roth?
You might also hear about something called a Mega Backdoor Roth.
It sounds similar, but it’s a different strategy.
A regular Backdoor Roth IRA starts with a Traditional IRA.
A Mega Backdoor Roth starts with certain employer 401(k) plans.
Some employers allow employees to contribute extra after-tax money to their 401(k) beyond the normal employee contribution limit.
If the plan also allows the appropriate Roth conversion or rollover, that extra money may be moved into a Roth account.
For 2026, the general limit for total employee and employer contributions to a defined-contribution plan is $72,000 for someone under 50.
But this doesn’t mean everyone can contribute $72,000 themselves.
Your employer’s contributions count toward that limit, and your plan must specifically allow additional after-tax contributions.
Regular Backdoor vs. Mega Backdoor Roth
| Feature | Backdoor Roth IRA | Mega Backdoor Roth |
|---|---|---|
| Where does it start? | Traditional IRA | Employer 401(k) |
| Who might use it? | People above Roth IRA income limits | People with eligible 401(k) plans |
| Extra IRA contribution limit? | No | Uses separate 401(k) plan limits |
| Does your employer need to allow it? | No | Yes |
| Is it available to everyone? | Depends on tax circumstances | No |
For beginners, I would focus on understanding the regular Backdoor Roth IRA first.
The Mega Backdoor Roth is an additional strategy worth exploring if your workplace retirement plan offers it.
9. One Important Tax Mistake to Avoid
Before using a Backdoor Roth IRA, check whether you already have money in a Traditional IRA.
Here’s why.
Imagine your Traditional IRA already contains $90,000 that hasn’t been taxed.
Now you add $10,000 of money you’ve already paid income taxes on.
Your account contains:
| Type of Money | Amount |
|---|---|
| Money not yet taxed | $90,000 |
| Money already taxed | $10,000 |
| Total | $100,000 |
You might think you can move only the $10,000 of after-tax money into a Roth IRA without paying additional taxes.
Unfortunately, the IRS doesn’t let you separate the money that way.
Instead, it generally treats the conversion as a mixture of both types of money.
In this simplified example, approximately 90% of the conversion would be taxable.
This rule is called the pro-rata rule.
You don’t need to memorize that name.
Just remember:
If you already have pretax money in a Traditional IRA, check the tax consequences before doing a Backdoor Roth IRA.
The IRS generally looks at your Traditional, SEP, and SIMPLE IRA balances together when calculating the taxable portion of a conversion.
A regular 401(k) balance generally isn’t included.
Also, the $10,000 amount above is only an illustration of the tax calculation, not a suggested annual IRA contribution.
Before making a conversion, consider asking a tax professional to review your existing accounts.
You also generally need to report nondeductible IRA contributions and Roth conversions on IRS Form 8606.
Source: IRS Form 8606 Instructions
10. Which Investment Account Should You Choose?
Here’s the easiest way to decide.
| Your Goal | Account to Consider |
|---|---|
| Receive employer matching contributions | 401(k) |
| Potentially lower your income taxes today | Traditional 401(k) or deductible Traditional IRA |
| Enjoy tax-free qualified withdrawals later | Roth IRA |
| Earn too much for direct Roth IRA contributions | Backdoor Roth IRA |
| Invest without annual contribution limits | Brokerage account |
| Keep investments accessible before retirement | Brokerage account |
For many families, the answer isn’t choosing just one account.
It’s understanding how different accounts can work together.
A 401(k) can help you save consistently through your paycheck.
A Roth IRA can provide tax-free income in retirement when its requirements are met.
A brokerage account can provide flexibility for goals before retirement.
And a Backdoor Roth IRA may help higher-income households access Roth savings when direct contributions aren’t allowed.
Final Thoughts: It’s Not Just How Much You Save
For years, I thought retirement planning was simply about putting money away every month.
But now I understand that choosing the right investment accounts can be just as important.
Two people might save the same amount of money and invest in the same funds, yet end up with different after-tax results because of how their accounts are structured.
You don’t need to understand every complicated financial term to get started.
Begin with the basics.
Understand your 401(k).
Learn the difference between Traditional and Roth IRAs.
Know when a brokerage account makes sense.
And if your income is too high for direct Roth IRA contributions, learn whether a Backdoor Roth IRA could be useful.
Building wealth isn’t just about making more money. It’s about making thoughtful decisions with the money you’ve already earned.
By Irene | Money Bloom Daily
Disclaimer: This article is for educational purposes only and does not constitute personalized financial, investment, or tax advice. Contribution limits, income restrictions, withdrawal rules, and tax treatment depend on individual circumstances. Consult a qualified professional before making Roth IRA conversions or major retirement decisions.
Leave a Reply