What should you consider when buying a house? From school districts and commuting time to property taxes and neighborhood demographics, here’s what I learned from my own home-buying experience.
The Biggest House Isn’t Always the Best House
When my husband and I started looking for a house, I didn’t realize how many things we needed to consider.
Location, school district, property taxes, transportation, neighborhood demographics, and, of course, the size of the house.
Buying a home wasn’t simply about finding a beautiful property.
It was about choosing where we wanted to build our family’s life.
Around the same time, my sister was also looking for a house.
We both worked in New York City, but we had different priorities.
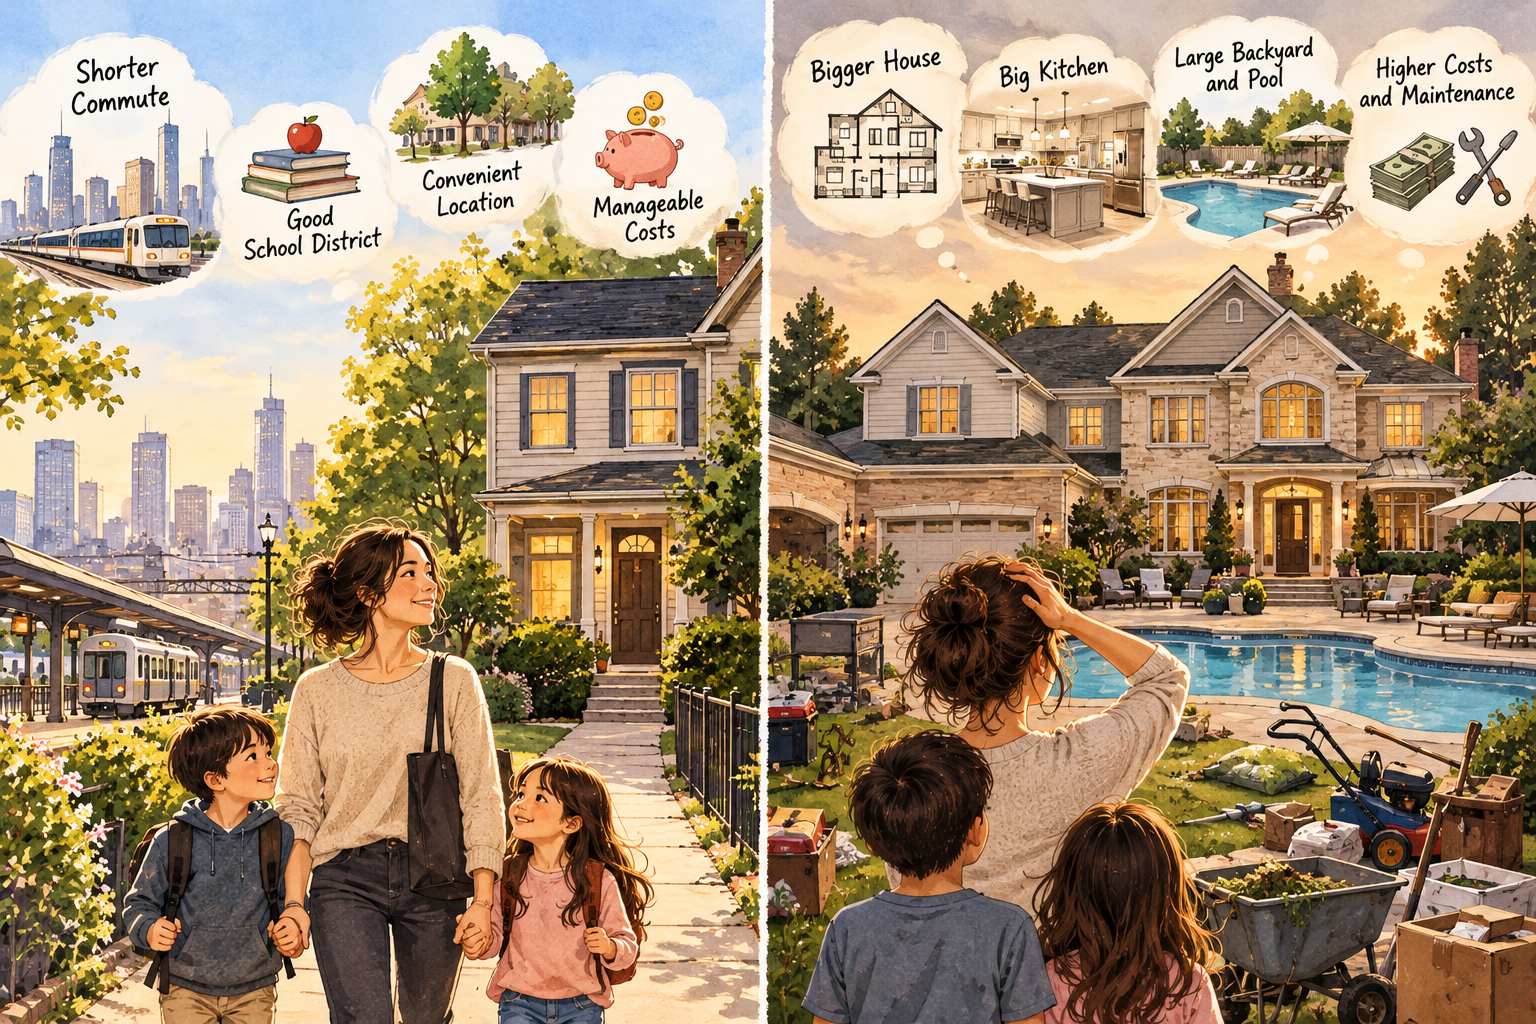
My sister wanted a larger property with a spacious kitchen, a big backyard, and possibly a swimming pool.
And honestly, who wouldn’t love those things?
I could easily imagine summer parties, children playing in the pool, and family gatherings in a beautiful kitchen.
But I kept asking myself one question.
Would I actually have enough time to enjoy all of that?
I’m not someone who frequently hosts large parties.
I’m not particularly interested in gardening.
And between working, commuting, and raising children, I knew my schedule would already be busy.
A beautiful backyard might look wonderful during an open house.
But would I enjoy maintaining it every weekend?
A swimming pool might sound amazing.
But would we use it enough to justify the expense?
That’s when I realized something important.
I didn’t need the biggest house I could afford. I needed a house that fit the life I actually lived.
Looking back, I’m glad I thought about it that way.
1. Location Was More Important Than Square Footage
Because I worked in New York City, commuting was one of my biggest concerns.
I knew moving to the suburbs would increase my travel time.
The location we eventually chose added approximately 30 minutes to my previous commute.
That was already a significant adjustment.
I didn’t want to move even farther away just to get a larger house.
Let’s think about what an additional 30-minute commute really means.
Assuming it’s 30 minutes longer in each direction:
| Additional Commuting Time | Time Lost |
|---|---|
| Each workday | 1 hour |
| Each week (5 days) | 5 hours |
| Each year (48 working weeks) | 240 hours |
| Over 10 years | 2,400 hours |
That’s approximately 100 full days spent commuting over 10 years.
And that’s only the additional travel time.
Imagine what you could do with those hours.
Spend more time with your children.
Exercise.
Cook dinner without rushing.
Work on a personal business.
Or simply relax after a long day.
When buying a house, we usually calculate the mortgage payment.
But how often do we calculate the value of our time?
A bigger house may give you more space, but a longer commute can take away the time you need to enjoy it.
Of course, some people work remotely or don’t mind commuting.
For them, a larger property farther from the city might be a wonderful choice.
But for my lifestyle, convenience mattered more.
2. School District Was Another Important Decision
As parents, we naturally wanted our children to have access to a good education.
So researching school districts became one of our priorities.
But I don’t think choosing a school district should be based only on its ranking.
A school might receive excellent academic ratings, but that doesn’t necessarily mean it’s the best environment for every child.
I wanted to understand the bigger picture.
What academic programs were available?
Did the district offer extracurricular activities?
Were there opportunities for children with different interests?
Would my children feel comfortable growing up in the community?
School rankings can be helpful, but they don’t tell the entire story.
And I wouldn’t recommend stretching your finances beyond what you can comfortably afford just to buy a house in the highest-ranked district.
A good school district matters.
But so does having enough money and time to support your children’s interests outside school.
3. Research the Neighborhood Before You Buy
This is one of the most important pieces of advice I would give anyone planning to purchase a home.
Don’t just research the house. Research the neighborhood.
When we were looking for a home, I wanted to understand the community where our family would spend the next several years.
Who lives in the area?
What is the general atmosphere?
Are there families with children?
Are there parks, libraries, supermarkets, and activities nearby?
Would I feel comfortable living there?
You can renovate a kitchen or replace flooring.
But you can’t easily change your home’s location or the community around it.
Start With Niche.com
One website I recommend exploring is Niche.com.
It’s a useful starting point for researching school districts and neighborhoods across the United States.
You can explore information such as:
- School district ratings: Compare academics, teachers, and student experiences.
- Neighborhood demographics: Learn about household characteristics, age groups, and community diversity.
- Housing information: Research home values and general housing trends.
- Community amenities: Explore parks, restaurants, and family-friendly activities.
- Resident reviews: Read about other people’s experiences living in the area.
I especially like the idea of comparing several towns before narrowing down your search.
However, I wouldn’t rely on a single website.
Niche ratings are helpful research tools, not guarantees of school quality or neighborhood satisfaction.
You should also check official school district information, visit schools when possible, and research local property taxes.
Visit the Playground
Here’s something I think many homebuyers overlook.
Visit the local playground.
Not just once.
Go on a weekend when families are likely to be outside.
Observe how the park is maintained and how people use the space.
Are children playing?
Do families seem comfortable spending time there?
Does it feel like a place where you would enjoy bringing your own children?
A playground can give you a glimpse of everyday community life that you won’t necessarily find in a real estate listing.
Visit the Local Supermarket and Bakery
I would also recommend visiting the local supermarket, bakery, or coffee shop.
Walk around.
Buy something.
Observe the atmosphere.
Can you imagine shopping there every weekend?
Does the area feel welcoming?
Are the stores and services you regularly use nearby?
For me, these everyday details matter.
A beautiful house may impress you during a 30-minute showing.
But you’ll spend years living in the surrounding neighborhood.
And feeling that you belong in a community is about more than its demographics. It’s about whether its atmosphere, amenities, and everyday lifestyle suit your family.
Visit at Different Times
A neighborhood can feel completely different depending on when you visit.
A quiet street on Sunday afternoon might have heavy traffic on weekday mornings.
A peaceful neighborhood during the day might be noisy in the evening.
Before making an offer, try visiting:
- During weekday commuting hours.
- On weekends when families are outside.
- In the evening to observe traffic, noise, and lighting.
If commuting is important, test the actual route to work.
Don’t rely only on an estimated travel time.
The best way to understand a neighborhood is to experience it—not just read about it.
4. Property Taxes Can Change What You Can Afford
One thing I learned about buying a house in New York is that the purchase price doesn’t tell the entire financial story.
Property taxes can make an enormous difference.
Imagine comparing two houses with the same purchase price.
| House A | House B | |
|---|---|---|
| Purchase price | $750,000 | $750,000 |
| Annual property taxes | $12,000 | $20,000 |
| Monthly property taxes | $1,000 | $1,667 |
| Annual difference | — | $8,000 |
These are hypothetical examples. Actual taxes depend on the property, local assessments, exemptions, and other factors.
Even though both houses cost $750,000, House B requires approximately $667 more every month in property taxes.
Over 10 years, that’s an $80,000 difference if the tax amounts remain unchanged.
And unlike a mortgage, property taxes don’t disappear when you pay off your home.
That’s especially important if you hope to stay in your house after retirement.
Before buying, I would always check the current tax bill and ask whether the amount could change after purchasing.
A house you can afford today should also make sense for your long-term financial future.
5. A Bigger House Comes With Bigger Responsibilities
My sister wanted a larger property.
I preferred something more manageable.
Neither approach is necessarily wrong.
But I think it’s important to understand what comes with additional space.
A larger home may mean:
- Higher heating and cooling bills.
- More cleaning and maintenance.
- Additional landscaping expenses.
- More expensive repairs.
- Higher insurance costs.
- Pool maintenance, if applicable.
For example, a swimming pool can be wonderful if your family uses it regularly.
But it also requires cleaning, chemicals, equipment maintenance, and potentially additional insurance expenses.
The same goes for a large backyard.
If you love gardening and spending time outdoors, it may bring tremendous enjoyment.
But if you work long hours and prefer spending weekends traveling or relaxing, maintaining a large property may feel more like another responsibility.
Before buying, ask yourself:
Am I paying for something I’ll actually enjoy—or something I simply like the idea of having?
That question can save you a lot of money and frustration.
6. The Hidden Cost of Living Farther Away
Let’s imagine two families choosing between homes.
Family A buys a smaller house closer to work.
Family B buys a larger house farther away.
Family B saves $100,000 on the purchase price.
That sounds like a great deal.
But suppose the longer commute adds $250 per month in transportation expenses.
Over 10 years, that adds up to:
$250 × 12 months × 10 years = $30,000
And that doesn’t include the value of the extra time spent traveling.
Of course, saving $100,000 on a home purchase could still make financial sense, even after considering commuting expenses.
The important thing is to compare the complete financial picture.
A cheaper house isn’t always cheaper to live in.
And a more expensive house in a convenient location isn’t automatically a bad investment.
The true cost of a home includes more than the mortgage.
7. What Should You Consider Before Buying a House?
If I were buying another home today, I would use this checklist.
| What to Consider | Questions to Ask |
|---|---|
| Location | Is it convenient for work, family, and everyday activities? |
| Commute | How much time and money will I spend traveling? |
| School district | Does the district offer programs that fit my children’s needs? |
| Neighborhood | Have I researched the community and visited local parks and shops? |
| Demographics | What can community data tell me about the area’s households, age groups, and diversity? |
| Property taxes | Can I comfortably afford them now and in retirement? |
| House size | Will my family actually use the extra space? |
| Maintenance | Do I have the time and budget to care for the property? |
| Transportation | Are trains, highways, and everyday necessities accessible? |
| Long-term plans | Will this home still fit our lives in 10 or 20 years? |
I would also recommend getting a professional home inspection, reviewing the property’s condition, and understanding the full monthly housing cost before making a final decision.
No house will check every box.
The goal is to understand which factors matter most to your family.
8. Think About the House You’ll Need 20 Years From Now
When buying a house, we often focus on what we need today.
But our lives change.
Children grow up.
Careers change.
Parents get older.
And eventually, we may retire.
A large home might be perfect while your children are young.
But will you still want to maintain the same property when they move out?
Will you enjoy taking care of a large backyard in your seventies?
Will you still be comfortable paying high property taxes after retirement?
Some people love having a large home throughout their lives.
Others prefer something smaller and easier to maintain.
There’s no universal right answer.
But I believe buyers should think beyond the next five years.
Especially if they’re hoping to purchase a long-term family home.
9. Looking Back, I’m Glad I Chose What Fit Our Lifestyle
Years later, when I look back at our home-buying decision, I feel good about the priorities we chose.
Our house may not have every feature I once imagined.
But it works for our family.
The location is convenient enough for our daily routine.
The school district was an important part of our decision.
And the property is manageable for our lifestyle.
Most importantly, I don’t feel that I sacrificed too much of my time simply to own a larger house.
When I think about my sister’s preferences, I still understand why she wanted more space.
A large kitchen, beautiful backyard, and swimming pool can bring a lot of enjoyment to a family that uses them regularly.
But those features weren’t as important to me.
And that’s the lesson I took away from our different priorities.
The right house for someone else may not be the right house for you.
Final Thoughts: Buy a House That Fits Your Life
Buying a home is one of the largest financial decisions most families will ever make.
But it’s also one of the most personal.
A house isn’t just an investment.
It’s where you return after a long day at work.
Where your children grow up.
Where you spend ordinary weekends.
Where you create memories.
And where you may eventually spend your retirement.
That’s why I believe choosing the right location and neighborhood is just as important as choosing the house itself.
Before falling in love with a beautiful kitchen or a large backyard, take time to research the community.
Visit the playground.
Stop by the local supermarket.
Walk around the neighborhood.
Test your commute.
And think about whether the lifestyle that comes with the house is truly the lifestyle you want.
I didn’t buy the biggest house I could afford. I bought the house that fit the life I actually live.
And looking back, I still believe that was one of the best decisions we made.
By Irene | Money Bloom Daily
Disclaimer: This article shares personal experiences and general home-buying considerations. Financial examples are hypothetical and are not personalized financial or real estate advice. Property taxes, housing expenses, and neighborhood conditions vary by location.
Leave a Reply